
Quantitative Methods Q174
174Ali, a CFA candidate, is evaluating a portfolio, which is composed of Fund A and Fund B. He has collected the following information:
| Fund A | Fund B | ||
| Portfolio weights (%) | 45 | 55 | |
| Expected returns (%) | 23 | 13 | |
| Standard deviations (%) | 14 | 6 | |
| Correlation between the returns of Fund X and Fund Y | 0.7 | ||
The portfolio standard deviation of the returns is closest to:


- Option : B
- Explanation : The portfolio standard deviation of the returns is calculated through
following formula:
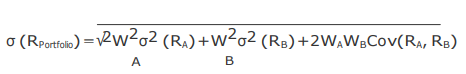 And covariance is calculated through following formula:
Cov(RARB)=ρ (RARB) σ (RA)σ(RB)
First calculate the covariance, Cov= 0.7 ∗ .14 ∗ .06 = 0.00588, then
enter values in the formula 1 for calculating portfolio standard
deviation, you should get portfolio standard deviation = 8.90%.

Accessibility
Oversized Widget
Saved in this browser. Nothing changes for anyone else.